Why More CRE Deals Need Equity in Today’s Market
Commercial real estate is not short on deals. It is short on well-structured capital.
Across the market, sponsors are facing a very different financing environment than the one that existed several years ago. Interest rates are higher, lenders are more selective, refinance proceeds are often lower, and many properties are approaching maturity with capital stacks that no longer work the way they were originally designed.
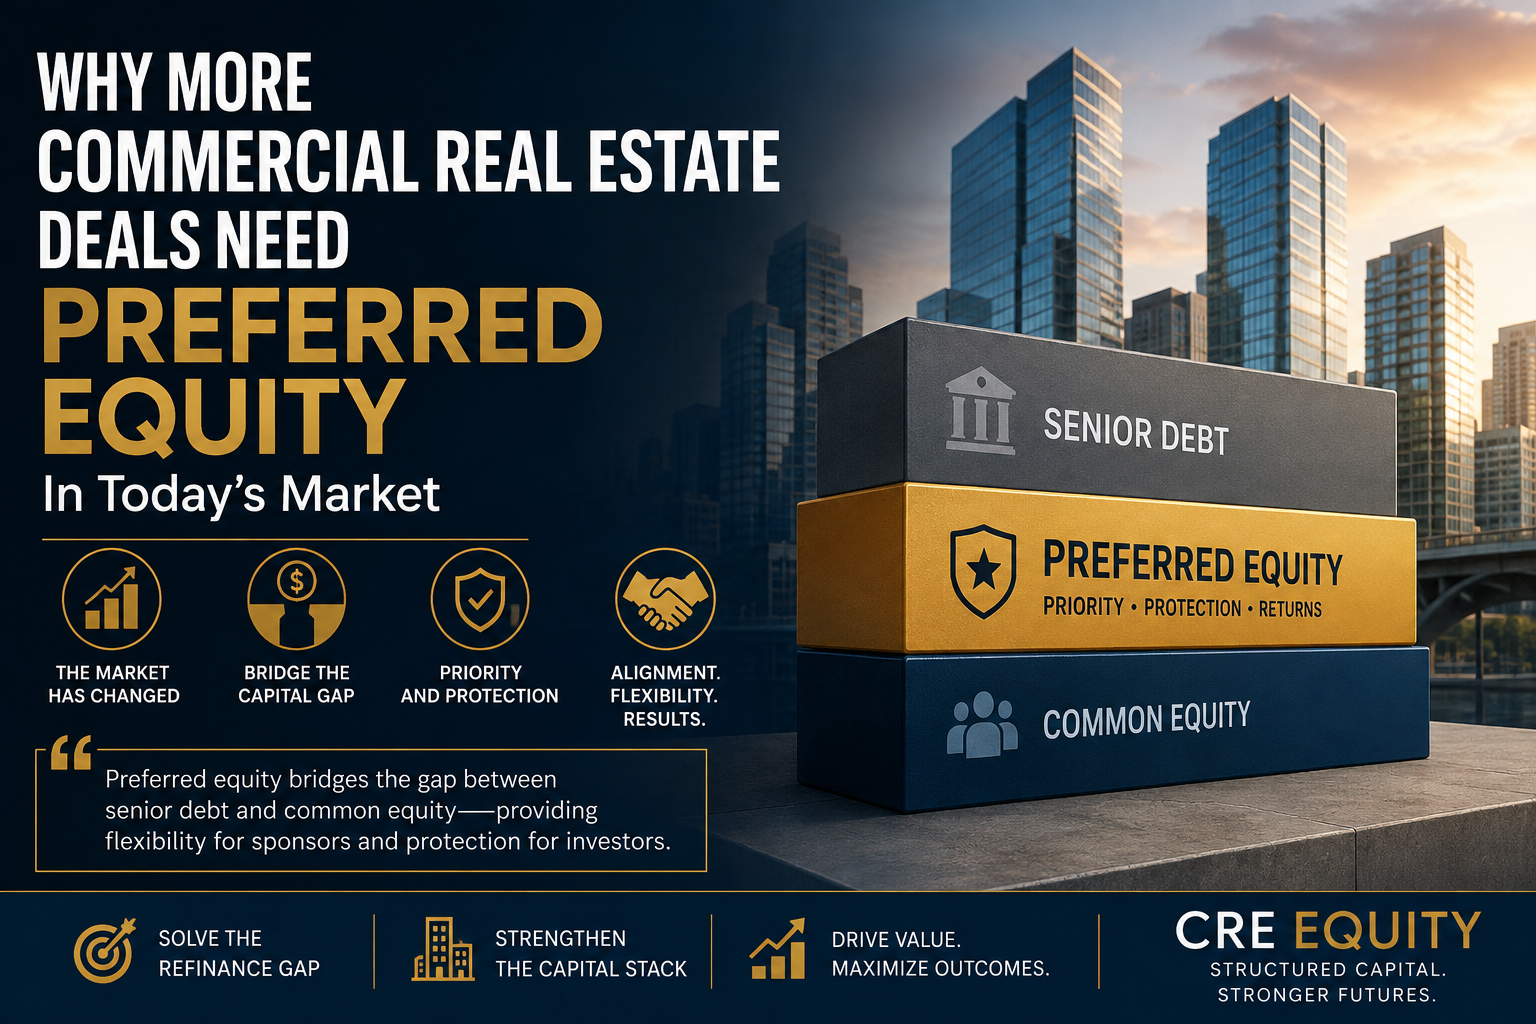
That is why preferred equity is becoming more important. Preferred equity is not just a way to add more money to a transaction. Used correctly, it can help bridge the gap between senior debt and common equity, provide sponsors with needed flexibility, and offer investors a more protected position in the capital stack. In today’s market, that structure matters.
The Refinance Gap Is the Real Issue
The commercial real estate market is dealing with a major wave of loan maturities. The Mortgage Bankers Association reported that approximately $929 billion of commercial and multifamily mortgage debt was scheduled to mature, and refinance pressure has continued as loans originated in a lower-rate environment come due.
The challenge is not always that the property is failing. In many cases, the asset may still be occupied, producing income, and performing reasonably well. The problem is that the existing loan was originated when interest rates were lower, debt proceeds were higher, and underwriting standards were more favorable.
Today, a new lender may underwrite the same property differently. Debt service coverage requirements may be tighter. Debt yield requirements may be higher. Cap rates may have moved. Operating expenses, insurance, taxes, and reserves may have increased.
The result is simple: the new loan may be smaller than the old loan, which creates a capital gap that gap has to be solved.
Why Preferred Equity Fits the Moment
When senior debt proceeds are not enough, sponsors typically have only a few choices. They can contribute more cash, raise additional common equity, sell the asset, pursue a workout, or bring in structured capital.
Preferred equity can be an effective solution because it sits between senior debt and common equity. It generally receives priority over common equity distributions, while still allowing the sponsor to preserve upside and continue executing the business plan.
For sponsors, preferred equity may help avoid a forced sale or an unnecessary dilution event.
For investors, preferred equity may offer a defined return, priority in the capital stack, and negotiated protections that are not typically available in common equity.
That is why more deals need preferred equity today. Not because every deal is distressed but because many deals need a better capital structure.
The Capital Stack Has Changed
In the previous cycle, sponsors could often rely on senior debt to fund a larger portion of the total capital need. Lower rates and stronger valuations allowed borrowers to refinance, acquire, renovate, and reposition assets with more leverage. That environment has changed.
Now, lenders are more focused on downside protection. They are looking carefully at cash flow, coverage ratios, tenant quality, market rent assumptions, exit values, and borrower strength. This shift pushes more responsibility onto the equity side of the capital stack.
That does not always mean common equity is the best solution. Common equity can be expensive, dilutive, and harder to raise in an uncertain market. Investors may also be reluctant to sit at the bottom of the capital stack unless the return potential is significant.
Preferred equity can help solve that problem by creating a structured position with priority over common equity, while still allowing the sponsor to maintain control of the business plan.
What Sponsors Need to Understand
Sponsors need to recognize that preferred equity investors are not simply filling a hole in the capital stack. They are underwriting risk. They want to know why the gap exists, how the preferred equity will be repaid, what protects their position, and whether the sponsor’s business plan is realistic in the current market.
That means sponsors need to be prepared to answer several important questions:
- What is the current loan balance?
- What will the new senior lender provide?
- How large is the capital gap?
- What is the property worth today?
- What is the stabilized value?
- How realistic is the exit strategy?
- What is the sponsor contributing?
- How is the preferred equity protected?
- What happens if the business plan takes longer than expected?
The more clearly a sponsor can answer those questions, the more credible the opportunity becomes.
Preferred Equity Is Not a Substitute for Good Underwriting
Preferred equity can be powerful, but it does not fix a bad deal. If the basis is too high, the senior debt is too large, the exit assumptions are too aggressive, or the sponsor is unwilling to align with investors; preferred equity will not make the transaction attractive.
The best use of preferred equity is in deals where the underlying real estate still makes sense, but the capital structure needs to be adjusted. That may include:
- A refinance where new loan proceeds are lower than expected.
- An acquisition where senior debt is limited by today’s underwriting standards.
- A value-add deal that needs additional capital to complete the business plan.
- A recapitalization where existing equity needs to be replaced or restructured.
- A stabilized asset where the sponsor wants to avoid selling in a weaker market.
In each case, the preferred equity should have a clear purpose, a defined repayment path, and a structure that matches the risk.
What Investors Are Looking For
Preferred equity investors are focused on risk-adjusted returns. They are not only looking at the preferred return. They are looking at the full structure of the investment. That includes the property basis, senior loan amount, sponsor equity, market position, exit strategy, cash flow, reserves, reporting requirements, and investor protections.
Important protections may include distribution priority, approval rights over major decisions, cash management provisions, redemption rights, default remedies, and restrictions on additional debt.
In today’s market, investors want to know that they are being paid appropriately for the risk they are taking and that their position is protected if the business plan changes. This is especially important when Treasuries and other lower-risk investments offer more attractive yields than they did in the prior cycle.
Why This Matters Now
The current market is forcing sponsors and investors to become more disciplined. Higher rates have changed the math. Lower leverage has changed the capital stack. More selective lending has changed the refinancing process and investors now have more alternatives when deciding where to place capital.
That does not mean commercial real estate is unattractive. It means the structure has to make sense.
Preferred equity is becoming more relevant because it addresses one of the central problems in today’s market: many properties still have value, but the existing capital stack no longer fits the current financing environment.
When used correctly, preferred equity can help sponsors preserve ownership, complete business plans, refinance existing debt, and avoid unnecessary sales. At the same time, it can give investors a priority position with defined economics and negotiated protections.
The Bottom Line
More commercial real estate deals need preferred equity because the market has changed. Senior debt is more constrained. Refinance proceeds are often lower. Investors are more selective. Sponsors need flexible capital and capital stacks that worked several years ago may not work today.
Preferred equity can help bridge that gap but it has to be structured correctly. The deals that will attract capital in this environment are not the ones with the most aggressive projections. They are the ones with strong basis, realistic assumptions, clear repayment paths, proper investor protections, and sponsors who understand the new capital markets reality.
In today’s market, preferred equity is not just an alternative source of capital.
It is becoming a necessary part of the commercial real estate capital stack.
Preferred equity capital for commercial real estate sponsors and investors. Capital. Relationships. Results.
This website is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy securities.